Equities
Weak Auction Clearance Rates, RBA Minutes and the Case for Small Caps
Christopher Gerace
5 min

Sydney and Melbourne auction clearance rates hit multi-year lows as the RBA's June minutes and a fuel subsidy cut loom. Plus, why fund managers see small caps entering an early rotation phase.
The Australian share market kicked off the week in positive territory, with technology and gold stocks among the day's standout performers. Away from equities, the weekend property auction results were a different story. In Sydney, fewer than half of all homes listed for auction sold, with a clearance rate of just 47.3%, the lowest we have seen since the early days of the COVID pandemic in April 2020. Melbourne was similarly quiet, with only 40.2% of auctioned homes finding a buyer, the weakest result in nearly four years. In simple terms, sellers are struggling to find buyers, and those that do are likely accepting lower prices than they might have hoped for. It is a trend worth keeping an eye on, especially as Australians wait to see where interest rates head next.
This week, all eyes will be on the RBA's June meeting minutes, which will give us a clearer picture of where interest rates are heading. With inflation still high and the jobs market holding strong, another rate rise cannot be ruled out. On the cost of living front, petrol prices are set to rise from Tuesday. Since April, the government had been subsidising 32 cents per litre at the pump to help ease pressure on household budgets. From 1 July, that subsidy drops to 16 cents per litre. The ACCC is keeping a close eye on retailers to make sure the change is passed on fairly and not used as an excuse to charge even more.
US markets ended last week on an indecisive note, with major benchmarks finishing mixed in a choppy, rangebound session. For the week, the Nasdaq bore the brunt of the selling, falling 4.60%, while the S&P 500 shed 1.95%. The Dow and Russell 2000 managed to hold their ground, posting modest gains of 0.60% and 1.02% respectively.
The AI trade remained front of mind for investors. Chipmakers came under pressure after reports emerged that OpenAI may push its IPO to 2027, raising fresh questions about the pace of AI infrastructure spending. Despite the near-term turbulence, Goldman Sachs maintained a constructive view, noting that retail investors have been the most consistent buyers of 2026 and that the broader trend remains higher, even as volatility persists.
Commentary from Industry Leaders
One theme gaining momentum among professional investors is the emerging case for small cap equities. History shows that every major technology cycle follows a consistent pattern, large cap concentration dominates early, before a broader rotation takes hold as the technology spreads through the wider economy. With market concentration currently sitting near record highs, many experienced fund managers believe we are in the early stages of that rotation now, and that the window to position ahead of it remains open.
What makes this cycle particularly interesting is the AI infrastructure buildout. Sustaining the pace of AI development requires enormous investment across power grids, cooling systems, network monitoring and data centre supply chains, most of which sits in the small cap universe and remains well off the radar of mainstream investors. For those willing to look beyond the obvious large cap names, the opportunity set is broad and, for now, largely undiscovered. The top-down noise around tariffs, geopolitics and AI narratives is actually masking what is, beneath the surface, a genuinely constructive earnings environment, with earnings beat rates running at multi-year highs and stock correlations beginning to normalise. These are historically the conditions that reward patient, bottom-up stock selection rather than passive or thematic approaches.
The challenge, of course, is execution. The small cap universe consistently rewards research-intensive investors who are prepared to look beyond standard analyst coverage and conventional screening. The businesses that tend to generate the most durable returns in this space share common characteristics, tight capacity, strong pricing power and management teams focused on compounding value over the long term rather than chasing short-term results. What separates the managers who perform in this space from those who do not comes down largely to the depth and breadth of their research capability, particularly the ability to track second and third-order effects across supply chains, commodity flows and regional dynamics that domestic analysis consistently misses.
For investors currently underweight small caps or sitting on the sidelines waiting for a clearer signal, the data from practitioners suggests the most compelling trigger to add exposure would be evidence of earnings recovery within the small cap index itself, followed closely by a widening of the valuation discount relative to large caps, both of which are worth monitoring closely in the months ahead.
Podcast Series
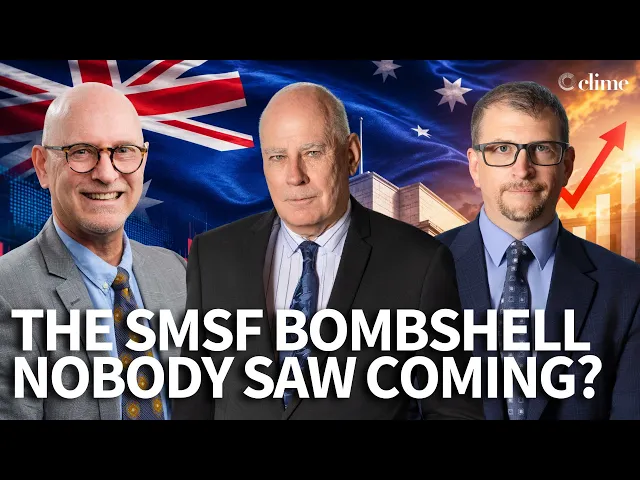
Our partners at Clime Investment Management release a weekly podcast covering the latest market and economic insights. This week, John Abernethy, Michael Baragwanath and Paul Zwi discuss inflation, employment and the proposed changes to investing in property through an SMSF. Click the preview below to tune in.
Economic News
In a significant development for SMSF trustees, Prime Minister Albanese and Treasurer Chalmers confirmed on 23 June 2026 that new limited recourse borrowing arrangements (LRBAs) for residential property inside SMSFs will be banned, as part of the deal struck with the Greens to secure Senate passage of the broader Tax Reform No. 1 Bill.
Existing arrangements are fully grandfathered and contracts already signed before the ban's commencement date are protected, even where settlement or loan approval is yet to occur. With the bill expected to pass the Senate before parliament rises on 2 July and royal assent typically following within days, the effective ban date is likely to fall around mid-August 2026.
Importantly, the legislation does not prevent SMSFs from investing in residential property altogether, it removes the borrowing pathway only, with LRBAs for commercial and business real property remaining fully available.
Market Snapshot
Australia: ASX to rise as EOFY reset outweighs Middle East fears.
United States: Dow -0.1%, S&P 500 -0.05%, Nasdaq -0.2%.
Bonds: US 10-year yield at 4.371% and Australian 10-year yield at 4.727%.
Gold: Increased overnight.


